AMIRA P754 metal accounting software
The AMIRA P754 Code of Practice for Metal Accounting sets out principles for making a mine’s reported metal production auditable and transparent. Here is what it asks for, principle by principle, and how MAX4METS helps your site meet it.
What is AMIRA P754?
AMIRA P754 grew out of a SAIMM workshop on the challenges of metal accounting, held in Cape Town in August 2001. AMIRA, the not-for-profit organisation through which mining companies fund shared research, started project P754 in 2003 with the sponsorship of Anglo American, Anglo Platinum, BHP Billiton, Kumba Resources and Rio Tinto. The intention was a code for metal accounting similar in concept to the JORC and SAMREC codes for reporting mineral resources and ore reserves. A team of industry and research representatives wrote the code over 2004 and 2005. It was first released in October 2005, revised in December 2005, and revised again as Release 3 in February 2007. The project's research also produced a textbook, An Introduction to Metal Balancing and Reconciliation, edited by Rob Morrison and published by the JKMRC at the University of Queensland. The code's aim is to make metal accounting auditable and transparent from mine to product, in support of good corporate governance.
The code describes a metal accounting system: the measurements of mass and metal content, the sampling and assaying, the calculations, the people and procedures, and the reports to management and the board. It sets ten principles that such a system must meet, along with best practices for the measurement, sampling and calculation that sit beneath them.
The principles are about governance. They ask whether every reported figure can be traced to its source, whether the method is consistent and documented, whether accuracy is known, and whether the system is audited. Those questions matter to finance and the audit committee as much as to the plant.
Why spreadsheets fall short
Month-end metal accounting kept in a chain of spreadsheets may produce the right figures, but on their own spreadsheets do not provide the controls the code asks for.
- No audit trail A spreadsheet cannot show who changed a figure, when or why.
- Dependent on one person The logic often lives in one metallurgist’s workbook and leaves with them.
- No separation of duties The person entering data can also change the formula and approve the result.
- Lost traceability Copied values quickly lose their link back to the laboratory or plant source.
The ten principles of AMIRA P754 and how MAX supports them
The principles below are summarised in our own words. For each one we say what MAX does and what remains your site’s own practice, because no software on its own makes a site compliant.
-
Principle 1: Accurate measurement and a check-in, check-out balance
The system rests on accurate measurements of mass and metal content, accounts for everything entering and leaving the operation to produce an ongoing metal balance, and passes its results one way to other management systems.
- How MAX helps
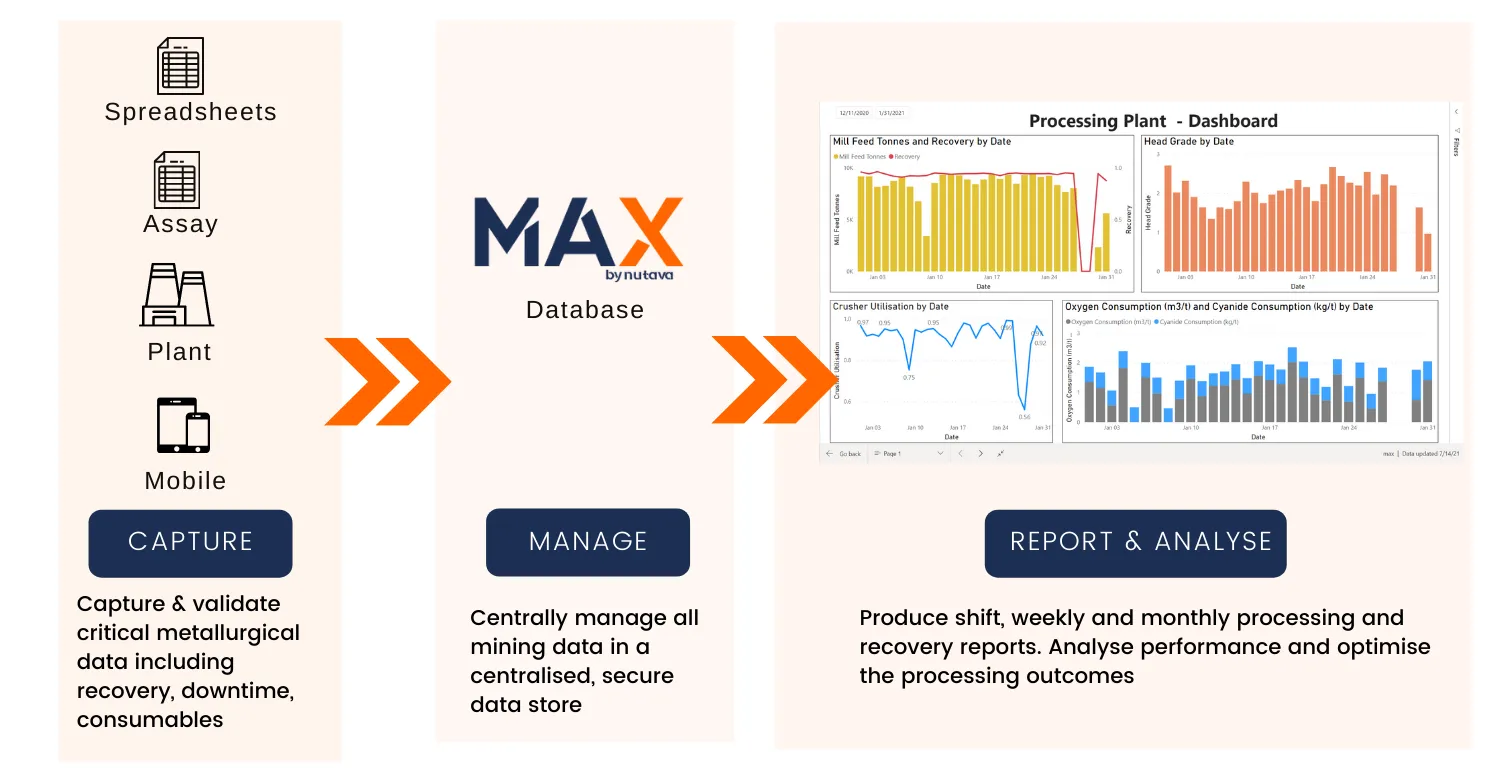
- Measure points for every stream and stock, imports of laboratory, plant system and spreadsheet files, and a mass and metal balance that ties feed, product, tailings and inventory together. Results flow out to reports and Excel, Word and PDF exports without being re-keyed.
- Your site’s part
- Weightometers, flowmeters, sampling and assaying accurate enough to account from.
-
Principle 2: Consistent, transparent and risk assessed
The source of every input must be clear to every user, and the design of the system must reflect a risk assessment of the whole metal accounting process.
- How MAX helps
- Every value records who entered it, when and from which source. Calculations are named formulas that any user can open, so there is no hidden logic behind a reported number.
- Your site’s part
- The risk assessment itself, and the decisions about which measurements the balance relies on.
-
Principle 3: Documented procedures, controls and audit trails
Procedures must be documented and easy for plant staff to follow so the system never depends on one person, with clear controls, audit trails and consistent calculation rules.
- How MAX helps
- The calculations live in the system rather than in one person’s workbook, with a log of changes, explicit aggregation rules for daily to monthly roll-ups, and separate rights to enter, review and approve.
- Your site’s part
- Written procedures for the people around the system, such as sampling, stock takes and month-end steps.
-
Principle 4: Regular internal and external audits
The system must be audited and reviewed regularly, internally and externally, including an assessment of risks and recommendations to reduce them.
- How MAX helps
- A log of edits with previous and new values, original values kept beside adjusted ones, a record of who approved each report, and lock dates that protect reported periods, so an auditor can trace a figure to its inputs.
- Your site’s part
- Scheduling the audits, appointing auditors and acting on their recommendations.
-
Principle 5: Timely results and documented investigations
Results must be available in time for operational reporting and corrective action. Each investigation is reported with management’s response, and the resulting action is signed off by the Competent Person.
- How MAX helps
- Shift, daily, weekly and monthly reports and dashboards are ready as soon as the data is in, reports can be generated automatically as each period ends and sent to distribution lists, and projects and tasks track investigations and improvement actions through to completion.
- Your site’s part
- Appointing the Competent Person and deciding which variances warrant an investigation.
-
Principle 6: Controlled provisional data and rogue data
Where provisional figures are used to meet a deadline, there must be clear procedures and authority for replacing them with final figures, and defined steps and authority levels for handling rogue data.
- How MAX helps
- Reports can be issued as preliminary and final versions, each approved and distributed separately. Import rules flag unknown and missing data, adjusted values are kept alongside the original measurement rather than overwriting it, and lock dates protect periods once they are reported.
- Your site’s part
- The rules for when provisional figures may be used and who may authorise their replacement.
-
Principle 7: Enough data to verify, reconcile and detect error
The system must produce enough data to verify results, handle transfers, reconcile balances, measure accuracy and detect errors, without consistent bias in measurement or calculation.
- How MAX helps
- Period reconciliation distributes measured totals, such as stock surveys or final assays, across the period and keeps each original value beside its reconciled value, so the size of every adjustment is visible. The full data set is available for further statistical analysis.
- Your site’s part
- Statistical studies of measurement and sampling error.
-
Principle 8: Target and actual accuracies
Target accuracies are set for the mass measurement, sampling and analysis of every stream used for accounting. The accuracies actually achieved are reported to the audit committee, and any bias the company considers material to its results is reported to shareholders.
- How MAX helps
- Holds the complete history of measurements, assays and adjustments that accuracy studies draw on, organised by stream and period.
- Your site’s part
- Setting target accuracies and calculating the achieved accuracies, for example through a sampling and measurement study.
-
Principle 9: Stock takes and inventory adjustments
In-process inventories must be verified by physical stock takes at set intervals, at least once a year, with defined procedures and authority for stock adjustments and unaccounted losses or gains.
- How MAX helps
- Stock surveys that set measured inventory balances against book balances, in-circuit and stockpile inventory tracking, and reconciliations that keep the original figures and can be locked once final.
- Your site’s part
- Carrying out the physical stock takes and setting the authority limits for adjustments.
-
Principle 10: Find and remove bias quickly
Every effort must be made to identify bias as quickly as possible and to remove or reduce its source in measurement, sampling and analysis.
- How MAX helps
- Data can be imported and reviewed through the month rather than at month end, and dashboards can trend accounted against measured figures so a drifting instrument or assay stands out.
- Your site’s part
- Investigating and fixing the instrument, sampler or laboratory procedure behind a bias.
Software is one part of a compliant system
The code is clear that the accuracy of a metal balance depends first on the measurements going into it. A biased weightometer or an unrepresentative sample will give a wrong answer however good the software is. A site working towards AMIRA P754 typically combines:
- a sampling and measurement review that sets target accuracies for each accounting stream;
- documented procedures and a Competent Person responsible for the metal accounting system;
- regular internal and external audits; and
- a metal accounting system that makes every figure traceable, controlled and repeatable.
MAX is that last part. It replaces the spreadsheets with one auditable system, so the time your metallurgists spent assembling the month-end can go into understanding the plant instead.
MAX4METS features behind these principles
Preparing for an AMIRA P754 audit?
See how MAX would hold your plant's data, formulas and approvals, and what an auditor would see.